Property tax compliance software: what it covers, and what it leaves to you
Last updated:
8 min read
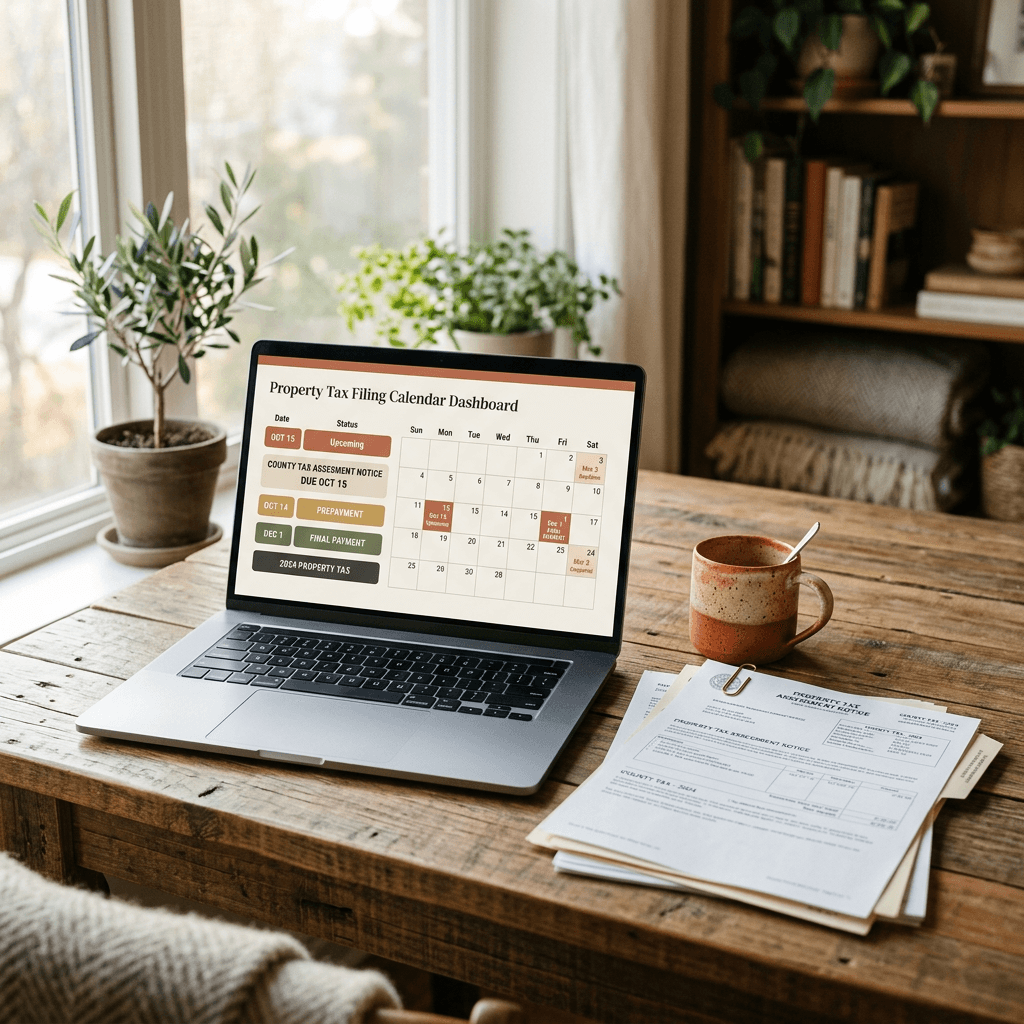
Property tax compliance software is the system a company uses to meet its property tax obligations as the taxpayer of record: preparing and filing business personal property renditions, tracking assessment notices and appeal windows, calculating accruals, and paying tax bills across every jurisdiction where it holds taxable property. It exists because the deadlines, forms and definitions of taxable property differ in every state and often in every county.
That is a real problem and the category solves it competently. The trouble starts with what the word compliance quietly excludes.
The compliance calendar it is built around
The category is organized around a recurring annual cycle, and most products in it are best understood as a calendar with a filing engine attached.
Renditions come first. In Texas, business owners must file a rendition with the county appraisal district by April 15, listing a good faith estimate of value for taxable inventory, furniture and fixtures, machinery, equipment and other property (Texas Comptroller of Public Accounts, April 2026). Other states set different dates, apply different exemptions, and draw the line between real and personal property in different places.
Assessment notices follow, each carrying its own protest window measured in days. Then tax bills arrive from thousands of separate taxing authorities, on their own schedules, and have to be validated, coded and paid before penalty dates. Accruals run alongside all of it so the expense lands in the right period.
A compliance system that does this reliably across four hundred sites is worth having. Missing a rendition deadline carries statutory penalties, and missing a payment date carries interest, and neither is an interesting way to lose money.
What compliance software cannot tell you
Compliance software answers one question: did we file and pay what was asked, on time. It does not answer the question that determines the size of the bill, which is whether what was asked was right.
The distinction is not academic. An assessor's value is an opinion produced at scale, usually by a mass appraisal model applied to a class of property rather than by anyone looking at your building. A compliance system will dutifully accrue, validate and pay a bill computed from an assessment nobody has tested. It will do that every year, on time, and the filing record will be spotless.
Testing the assessment is a different discipline with a different clock. It runs on protest windows rather than filing deadlines, it needs comparable sales and income evidence rather than an asset ledger, and it produces an appeal rather than a return. The evaluation criteria for that side of the work are covered in commercial property tax appeal software, and the windows themselves vary enough to be worth a reference: see property tax appeals by jurisdiction.
The same gap applies to incentives. A compliance system files what you tell it to file. It has no view on whether a site sits inside an enterprise zone, qualifies for a PILOT arrangement, or carries a historic preservation abatement nobody claimed, which is the subject of finding eligible tax programs.
The exposure with no return attached
Here is the part the category does not address at all, and it is usually the larger number.
If your company leases most of its locations, you are not the taxpayer of record on the buildings you occupy. The landlord owns the real property, receives the assessment notice, holds the protest right, and pays the bill. Under a triple net or modified gross lease, that tax then arrives in your operating expense statement as a pass-through, usually as a pro rata share, often as an estimate trued up later.
So the real property tax on a leased portfolio behaves like this: you pay it, you did not file it, you never saw the assessment behind it, you may have no contractual right to protest it, and it does not appear anywhere in your property tax compliance system because you have no obligation to file. It shows up in accounts payable as part of a landlord statement.
That is a substantial cost sitting outside the control environment built for property tax. The control that governs it is not the return. It is the lease: the tax clause, the definition of the tax year, the pro rata share calculation, the treatment of special assessments, and whether the lease gives the tenant the right to compel or participate in an appeal. Verifying those terms against what was billed is pass-through work, the same discipline applied to auditing pass-through charges, and it depends on the tax clause being abstracted accurately in the first place (lease abstraction).
How property tax obligations split across a leased portfolio
| Obligation | Who files | Who ultimately pays | What compliance software does | What it cannot tell you |
|---|---|---|---|---|
| Business personal property at sites you operate | You | You | Prepares and files the rendition, tracks each jurisdiction's deadline | Whether the asset ledger still carries equipment you disposed of, or items already taxed as real property |
| Real property tax on a leased site | The landlord | You, through pass-throughs | Nothing. You are not the taxpayer of record | Whether the assessment is defensible, whether the billed amount matches the lease's tax clause, whether your pro rata share is calculated correctly |
| Real property tax on owned sites | You | You | Tracks the notice, books the accrual, validates and pays the bill | Whether the assessed value exceeds market, and whether the protest window is still open |
| Tenant-funded leasehold improvements | Depends on the jurisdiction and the lease | You, directly or through pass-through | Files them where they are classified as personal property | Whether the same buildout is also inside the landlord's real property assessment |
| Abatements and incentive programs | You or the landlord | Benefit flows according to the lease | Tracks the filing where you administer it | Whether a site qualifies for a program nobody has claimed |
The fourth row is the one worth pausing on. When a tenant funds a buildout, the improvements can be rendered as the tenant's personal property in some jurisdictions and captured in the landlord's reassessed real property value in others, and sometimes both happen. The tenant pays the personal property tax directly and pays a share of the increased real property tax through the operating expense statement. Two bills, one buildout, and no single system holding both sides of the picture, because the rendition lives in the tax department and the pass-through lives in accounts payable.
What to do with this
Nothing here argues against compliance software. If you file renditions in thirty states, you need a system that files renditions in thirty states, and building that on spreadsheets is how penalty notices happen.
The argument is about scope. Buying a compliance platform and treating property tax as handled leaves two larger questions unowned. Whether the assessments you are paying against are defensible, and whether the tax your landlords bill you matches what the leases actually say. Both are recovery work rather than filing work, both run on their own deadlines, and neither one will be flagged by a system whose definition of success is an on-time filing.
The practical version is a short set of questions for whoever owns occupancy cost. Which of our sites did we pay real property tax on last year without seeing the assessment behind it. Which leases give us the right to protest or to require the landlord to. Where do our rendered assets and our landlords' assessed improvements overlap. How many tax pass-through line items did anyone check against the lease. Those questions sit in financial operations, and answering them across a portfolio is what tax auditing is built to do: comparing property records against county assessments, auditing landlord tax charges against lease terms, and identifying programs the portfolio qualifies for.
Compliance keeps you out of trouble. It was never designed to tell you the number was wrong.
FAQ
Is property tax compliance software the same as property tax appeal software?
- No. Compliance software manages the obligations of the taxpayer of record: rendition filing, assessment notice tracking, accruals and bill payment across jurisdictions. Appeal software supports challenging an assessed value, which needs valuation evidence, comparable data and protest deadlines rather than filing calendars. Some vendors sell both, but they are separate workflows with separate clocks, and buying one does not cover the other.
Do tenants need property tax compliance software?
- A tenant needs it for its own business personal property, meaning the furniture, fixtures, equipment and inventory it owns at each site, wherever the jurisdiction requires a rendition. It does not cover the real property tax the tenant pays through lease pass-throughs, because the tenant is not the taxpayer of record on the building. That exposure is governed by the lease and reviewed as a pass-through audit.
What is a business personal property rendition?
- A rendition is a filing that reports the taxable personal property a business owns at a location, typically with the owner's good faith estimate of its value. In Texas it covers inventory, furniture and fixtures, machinery and equipment, and it is due to the county appraisal district by April 15 (Texas Comptroller of Public Accounts). Other states set their own deadlines, exemptions and definitions of taxable property.
Can compliance software tell us whether we are overpaying property tax?
- Not by design. It confirms that a return was filed and a bill was paid on schedule. Determining whether the assessed value is supportable, or whether a landlord's tax pass-through matches the lease, requires comparing the assessment against market evidence and the billed charge against the tax clause. Those are review activities, and they run on protest windows and lease audit rights rather than on the filing calendar.
More From Our Blog
More
Filing property tax appeals across every jurisdiction
Why assessment review is a portfolio problem, and how to surface the appeals worth filing first.
Finding the tax programs your sites already qualify for
Abatements, PILOTs, and enterprise zones go unclaimed. A way to surface eligibility across the portfolio.
Commercial property tax appeal software: what to evaluate before you buy
Most property tax appeal software manages appeals you already decided to file. The harder job is deciding which assessments to challenge.
Initial agents live in two weeks.
Start with one or two high-value workflows, connect the required data and documents, measure the result, then expand across domains.
- A tailored onboarding for every enterprise.
- Fitted to how you actually work.
- Continuous support as your portfolio evolves.